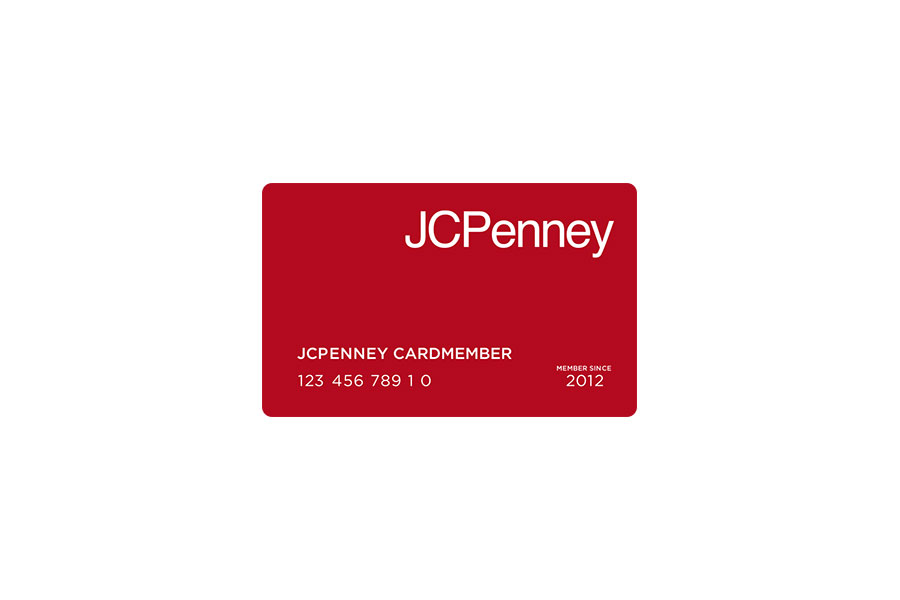
Synchrony Bank doesn’t publish a minimum credit score for the JCPenney Credit Card. Approval depends on your overall credit profile, and JCPenney offers both a store card and a Mastercard version.
You can also check for prequalification before you submit a full application. The prequalification check won’t affect your credit score, so it’s a useful first step if you aren’t sure whether your credit profile is ready.
What Credit Score Do You Need for a JCPenney Credit Card?
Current third-party guidance generally places the JCPenney Credit Card in the fair-credit range, with a credit score around 640 as a reasonable benchmark for the store card.
Synchrony Bank doesn’t identify that number as an official minimum. An applicant with a lower credit score may qualify, while someone with a higher credit score can still be denied because of other factors.
The JCPenney Mastercard can require a stronger credit profile because it works anywhere Mastercard is accepted. The store-only JCPenney Credit Card has more limited use and may be easier to qualify for.
Your income, existing debt, payment history, credit utilization, recent applications, and overall credit history can all affect the final decision.
Check for Prequalification Before You Apply
JCPenney and Synchrony Bank let you check for prequalification without affecting your credit score.
That gives you useful information before you submit a full application and risk a hard inquiry on your credit report.
Prequalification doesn’t guarantee approval. Synchrony Bank still needs to complete its review after you formally apply.
If you don’t prequalify, consider improving your credit profile before submitting a full application.
JCPenney Credit Card vs. JCPenney Mastercard
JCPenney offers two credit card versions.
The JCPenney Credit Card is a store card. You can use it at JCPenney stores and JCPenney.com.
The JCPenney Mastercard works at JCPenney and anywhere else Mastercard is accepted.
Both cards can earn enhanced CashPass Rewards on qualifying JCPenney purchases. The Mastercard can also earn rewards on eligible purchases outside JCPenney.
The Mastercard generally makes more sense if you want a card that you can use for everyday purchases. The store card can still provide the main JCPenney cardholder benefits if you only plan to use the account at JCPenney.
What Else Can Synchrony Bank Consider?
Synchrony Bank doesn’t publish its approval formula. Your credit score is only one part of the application.
Several other factors can affect the decision:
- Payment history: Recent late or missed payments can weaken your credit profile.
- Income: Synchrony Bank can consider whether your income supports another credit account.
- Existing debt: High monthly debt obligations can leave less room for another payment.
- Credit utilization: Large balances compared with your available revolving credit can hurt your credit score and make your credit profile look stretched.
- Recent applications: Several recent hard inquiries can show that you’ve been seeking multiple new accounts.
- Credit history: A longer history of responsible credit use gives Synchrony Bank more information about how you manage debt.
Previous experience with other Synchrony Bank accounts may also give the issuer more information about your account history. An existing Synchrony Bank account doesn’t guarantee approval.
How JCPenney CashPass Rewards Work
JCPenney cardholders earn more CashPass Rewards on qualifying JCPenney purchases than basic Rewards members.
New cardholders begin at the Insider tier. Qualifying purchases earn 1.5 points per $1 spent, and every 200 points converts to a $10 CashPass Reward.
That works out to about 7.5% back in JCPenney rewards.
Cardholders who reach VIP status after $1,000 in qualifying JCPenney spending during a calendar year can earn 2 points per $1. That equals about 10% back in CashPass Rewards.
CashPass Rewards aren’t unrestricted cash back. You use them toward qualifying JCPenney purchases.
The JCPenney Mastercard Earns Rewards Outside JCPenney
The Mastercard version extends the rewards program beyond JCPenney purchases.
Current benefits include:
- 1% back: Earn 1% in CashPass Rewards on eligible purchases outside JCPenney.
- 5% back for the first 90 days: New Mastercard cardholders can earn 5% back on eligible gas station and grocery store purchases during the introductory period.
- $0 annual fee: Neither JCPenney card charges an annual fee.
- $10 birthday reward: Eligible cardholders can receive a $10 CashPass birthday reward.
- Cardholder events: Cardholders can receive access to Credit Savings Days and other offers.
The Mastercard also includes eligible Mastercard benefits, such as ID Theft Protection and Mastercard Global Services.
The High APR Can Erase Your Rewards
The rewards can be valuable for frequent JCPenney shoppers, but carrying a balance can quickly offset what you earn.
New accounts currently have a 33.24% variable purchase APR. The penalty APR can reach 39.99%.
That makes paying your statement balance in full especially important.
You don’t need to carry a balance to earn rewards or build credit. Paying your statement balance by the due date lets you keep the rewards without adding avoidable interest charges.
Special Financing Requires a Payoff Plan
JCPenney sometimes offers promotional financing on qualifying purchases.
Read the specific financing terms before you use an offer. Retail financing promotions can come with conditions that make the balance expensive if you don’t pay it off on time.
Don’t assume the minimum payment will eliminate the promotional balance before the deadline.
Calculate the monthly amount required to clear the balance early. Build some extra time into the payoff schedule instead of planning your final payment for the last possible month.
How to Improve Your Approval Chances
If your credit profile needs work, focus on issues Synchrony Bank can see when it reviews your application.
Start with the areas that can affect both your credit score and your overall application:
- Check for prequalification: See whether Synchrony Bank shows you an offer before you submit a full application.
- Lower revolving balances: Paying down credit card debt can reduce your credit utilization after the lower balances reach the credit bureaus.
- Keep payments current: Pay every account by its due date.
- Review your credit reports: Check your credit reports from Experian, Equifax, and TransUnion for inaccurate late payments, incorrect balances, unfamiliar accounts, and other errors.
- Limit new applications: Avoid adding hard inquiries for credit accounts you don’t need.
- Dispute inaccurate information: Contact each credit bureau that displays incorrect or incomplete information.
Crossing one specific credit score threshold isn’t the goal. A cleaner overall credit profile can improve your position regardless of the exact number.
Ready to take action on your credit?
Get your personalized plan in 30 seconds. Free, no credit check.
When a JCPenney Credit Card Makes Sense
The JCPenney Credit Card can make sense if you shop at JCPenney regularly enough to use CashPass Rewards and cardholder offers.
The store card offers the core JCPenney benefits, while the Mastercard adds wider acceptance and additional earning opportunities outside JCPenney.
The prequalification option also gives you a low-risk way to check where you stand before you submit a full application.
If you pay your balance in full and regularly shop at JCPenney, the rewards can provide solid value. If you expect to carry debt, the high interest rate can outweigh those savings quickly.