Your bank routing number is a nine-digit code that identifies your bank or credit union when money moves into or out of your bank account. You may need it to set up direct deposit, make an ACH payment, pay bills, or send certain bank transfers.
You can usually find your routing number on a check, through online or mobile banking, by contacting your bank, or with the American Bankers Association’s routing number lookup tool. Before using it, make sure you have the right routing number for the transaction. Some financial institutions use different routing numbers for ACH payments and wire transfers.
What Is a Bank Routing Number?
A bank routing number is a nine-digit number used to identify a U.S. financial institution during a financial transaction. It’s also called an ABA routing number or routing transit number.
The routing number identifies the financial institution, while your account number identifies your specific bank account. A large bank may have several routing numbers based on location or transaction type, while a smaller bank or credit union may use one routing number.
How to Find Your Bank Routing Number
There are four easy ways to find a bank routing number. The best option depends on whether you have a paper check and what type of transaction you’re setting up.
1. Find the Routing Number on a Check
If you have a personal check, look at the numbers printed along the bottom. The routing number is the nine-digit number in the bottom-left portion of the check.
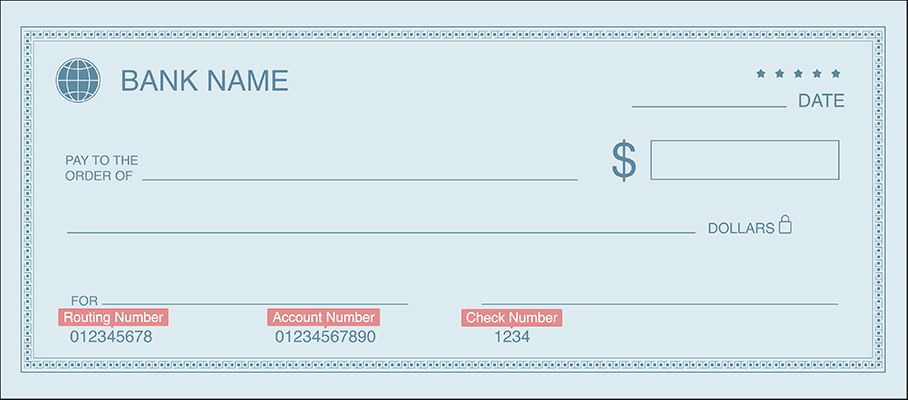
You’ll typically see your routing number, account number, and check number along the bottom of a personal check. The routing number identifies the financial institution, while the account number identifies your individual bank account.
The exact placement of the account number and check number can vary by check, so don’t rely only on the order of the numbers. The routing number will contain nine digits and appear between the routing symbols printed in magnetic ink.
Keep in mind that the routing number printed on a check may not be the routing number your bank uses for wire transfers.
2. Find the Routing Number in Online or Mobile Banking
Sign in to your bank’s website or mobile banking app and select the bank account you plan to use. Banks commonly display the routing number under account details, direct deposit information, or a similar section.
You can also check a recent bank statement. Some financial institutions include the routing number with other bank account details on monthly statements.
If you’re setting up a wire transfer, don’t assume the routing number displayed with your checking or savings account is the correct one. Check your bank’s wire transfer instructions before sending money.
3. Contact Your Bank or Credit Union
Your bank or credit union can provide the correct routing number by phone, secure message, online chat, or at a branch.
Tell the bank what you’re trying to do. The correct routing number may depend on whether you’re setting up direct deposit, making an ACH payment, or sending or receiving a wire transfer.
The bank may ask you to verify your identity before providing information about your specific bank account.
4. Use the ABA Routing Number Lookup Tool
The American Bankers Association provides an online routing number lookup tool that lets you search for or confirm a financial institution’s routing number.
You can search by financial institution name, city, and state, or enter a routing number to identify the financial institution associated with it.
The ABA lookup is helpful when you want to confirm a routing number, but finding a routing number associated with a bank doesn’t mean it’s necessarily the right one for your bank account or transaction. Check with the financial institution when you’re unsure.
How to Know Which Routing Number to Use
The correct routing number depends on the bank and the type of transaction. Some financial institutions use the same routing number for several types of transactions, while others use different routing numbers.
Here are the main transaction types to check:
- Direct deposit: Employers and government agencies generally need the routing number and account number associated with your bank account for electronic deposits.
- ACH payments: Automatic bill payments, transfers between bank accounts, and other ACH transactions typically require an ACH routing number.
- Domestic wire transfers: Some banks use a separate routing number for incoming or outgoing domestic wire transfers.
- International wire transfers: International transfers may require a SWIFT or BIC code and other banking information instead of relying on a U.S. routing number alone.
If you’re sending a large payment or an important transfer, confirm the required banking instructions directly with the recipient or financial institution before submitting it.
For more information about how bank wires work, see our guide to wire transfers.
Routing Number vs. Account Number
Routing numbers and account numbers work together, but they identify different things.
| Routing Number | Account Number | |
|---|---|---|
| What it identifies | A financial institution | Your specific bank account |
| Typical length | 9 digits | Varies by financial institution |
| Unique to you | No | Yes |
| Common uses | Direct deposit, ACH payments, checks, and some transfers | Identifying the bank account sending or receiving money |
Several customers at the same bank may use the same routing number. Your account number, on the other hand, is assigned to your individual bank account.
Don’t confuse either number with your debit card number. A debit card number identifies the card associated with your bank account and serves a different purpose.
What Are Bank Routing Numbers Used For?
Routing numbers help financial institutions determine where money should be sent or collected. They’re commonly used with your account number to process transactions.
Common uses include:
- Direct deposit: Routes paychecks, government benefits, and other electronic deposits to the correct financial institution.
- ACH transfers: Helps move money electronically between bank accounts.
- Automatic bill payments: Allows companies to withdraw authorized payments from a bank account.
- Check processing: Identifies the financial institution responsible for paying a check.
- Wire transfers: May be required for domestic wire transfers, although some banks use separate wire routing information.
The routing number identifies the financial institution. Your account number tells the financial institution which bank account should receive or send the money.
Common Routing Number Mistakes to Avoid
A routing-number error can delay a transaction or cause it to be rejected. Check the information carefully before submitting a payment or transfer.
- Confusing the routing number with the account number: A routing number identifies the financial institution, while an account number identifies your specific bank account.
- Entering the digits incorrectly: Routing numbers contain nine digits. Double-check the entire number before submitting a transaction.
- Using an outdated routing number: Routing numbers can change after bank mergers, acquisitions, consolidations, or other changes. Confirm old banking information before using it.
- Using the wrong routing number for a wire transfer: The routing number on your check may not be the same number your financial institution uses for wire transfers.
- Leaving out the ninth digit: All ABA routing numbers contain nine digits. The ninth digit serves as a check digit that helps validate the routing number.
Do Routing Numbers Ever Change?
Yes. A routing number can change after a bank merger, acquisition, consolidation, or other change involving a financial institution.
Banks may continue accepting an old routing number for some transactions during a transition period, but you shouldn’t assume an old number will continue working. Check current instructions through your financial institution before setting up a new payment or transfer.
This is especially important if you’re using banking information from an old check, deposit slip, or saved payment record.
What Routing Information Do You Need for an International Transfer?
U.S. ABA routing numbers aren’t the standard bank identifier used in every country. The information required for an international transfer depends on the countries, financial institutions, and payment network involved.
An international transfer may require:
- SWIFT or BIC code: Identifies a financial institution for many international transfers.
- IBAN: Identifies a specific bank account in countries that use the International Bank Account Number system.
- Account number: Identifies the recipient’s individual bank account.
- Bank name and address: May be required as part of the recipient’s banking instructions.
- Country-specific bank codes: Some countries use their own bank or branch identification systems.
- Correspondent bank information: Certain international transfers pass through another financial institution before reaching the recipient’s bank.
Don’t assume every international bank account has an IBAN. Requirements differ by country. Ask the recipient for the exact incoming wire instructions provided by their financial institution before sending money.
Frequently Asked Questions
Can two banks have the same routing number?
An active ABA routing number identifies a particular financial institution or processing endpoint within the U.S. banking system. You shouldn’t assume that two unrelated banks can use the same active routing number simply because they operate in the same area.
Can one bank have multiple routing numbers?
Yes. Large financial institutions may have multiple routing numbers. The correct routing number can depend on where the bank account was opened or the type of transaction you’re making.
Is a routing number sensitive information?
A routing number isn’t private in the same way as a password or PIN. Many customers at the same financial institution can share the same routing number, and routing numbers can be publicly searched.
Your routing number can become more sensitive when it’s combined with your account number and other personal information. Be careful about where you enter or share complete bank account details.
Can I find a routing number with just a bank name?
You may be able to find possible routing numbers with a bank name, but that may not be enough to determine which one applies to a specific bank account. Large banks can have multiple routing numbers.
The ABA routing number lookup lets you search using a financial institution’s name and location. If several routing numbers are possible, confirm the correct one with the bank.
What happens if I use the wrong routing number?
The result depends on the transaction and the number you entered. A payment or transfer may be rejected, delayed, or returned if the routing information doesn’t match the required financial institution.
If you’ve already submitted a transaction with an incorrect routing number, contact your bank or payment provider as soon as possible. Don’t submit a second transaction until you know what happened to the first one.